What is the market overview and industry significance of the Aerospace Materials Market?
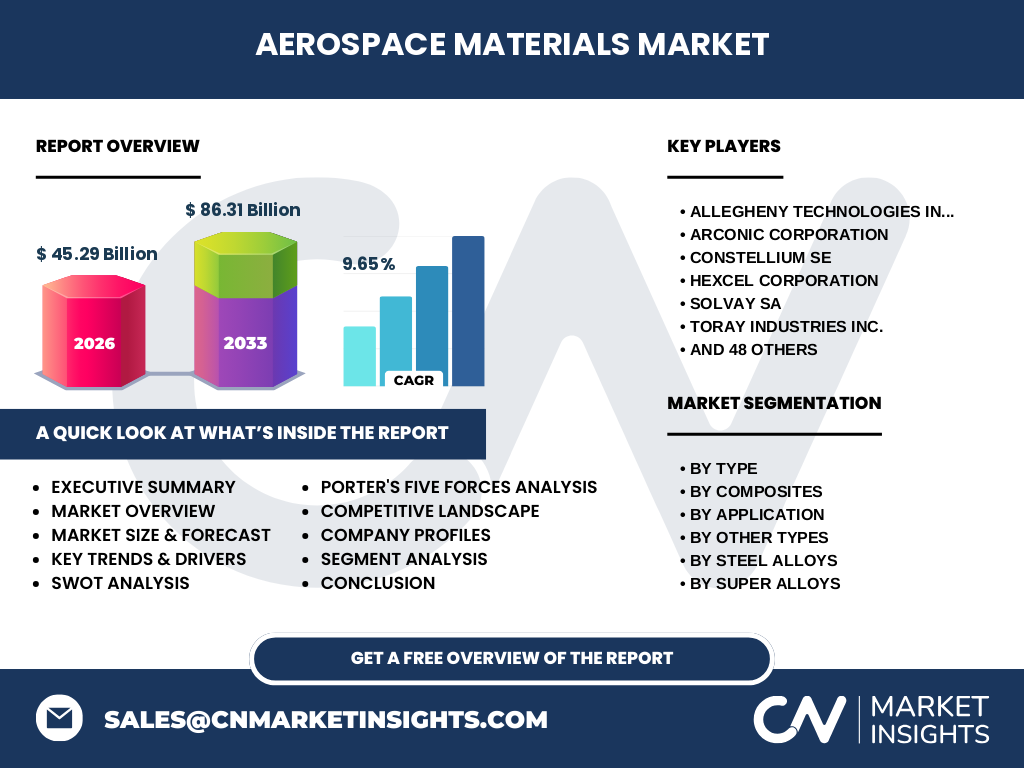
Our analysis indicates that the Aerospace Materials Market is valued at 45.29 Billion in 2026, driven by critical structural and propulsion demands. This sector encompasses advanced metallurgy and high-performance polymers essential for regulatory compliance with agencies like the FAA and EASA. Industrial significance lies in enabling lightweighting strategies that directly reduce jet fuel consumption and carbon emissions across commercial and military fleets.
Structural Growth Drivers and Market Restraints
The primary catalyst is the surging global aircraft backlog, which compels suppliers to scale production rapidly. However, supply chain bottlenecks in raw sponge titanium and strict aerospace certification timelines act as notable restraints. Opportunities thrive in substituting legacy metals with advanced composites to meet stringent net-zero carbon mandates set by international civil aviation authorities.
Emerging Trends and Growth Patterns in the Industry
The shift toward automated tape placement for Carbon Fiber Reinforced Polymers is redefining structural manufacturing efficiency. Industry trends highlight increased adoption of Nickel-Based Super Alloys for extreme turbine operating temperatures. Growth patterns show robust demand originating from narrowbody aircraft fleet renewals and rising passenger traffic across Asia-Pacific logistics hubs.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted the supply chain, causing historic production halts across major tier-1 facilities and grounding global fleets. Our research shows the recovery trajectory is anchored by robust narrowbody demand. Companies like The Boeing Company and Airbus Defence and Space have restructured supply networks, accelerating the market toward a projected 86.31 Billion valuation by 2033.
Competitive Benchmarking and Market Concentration
Market concentration is moderately high, dominated by specialized metallurgists and chemical conglomerates like Hexcel Corporation, Solvay SA, and Toray Industries Inc. Strategic dynamics involve aggressive vertical integration and joint ventures aimed at securing proprietary resin formulations and high-grade aluminum supply streams to outpace regional competitors.
Executive Summary of Key Findings
The Aerospace Materials Market is poised for exceptional expansion, registering a robust 9.65% CAGR from 2027 to 2033. Our comprehensive findings reveal that material innovation in super alloys and composites remains the primary differentiator for tier-1 suppliers navigating fluctuating raw material costs and stringent airworthiness certifications.
Market Forecast from 2027 to 2033
Based on our research, the market will expand from its 2026 baseline of 45.29 Billion to reach 86.31 Billion by 2033 at a 9.65% CAGR. This accelerated trajectory is powered by widebody production rate increases and sustained defense modernization programs requiring advanced Titanium Alloys.
Segmentation Analysis of Core Material Categories
Segmentation is categorized by type, including Aluminum Alloys (featuring 2xxx, 5xxx, and 7xxx series), Steel Alloys, Titanium Alloys, Super Alloys, and Composites. Composites are further divided into CFRP, GFRP, and Aramid Fiber. Application segments cover Interior and Exterior domains, serving commercial, military, and general aviation aircraft types.
Regional Market Analysis and Geographic Distribution
North America dominates global consumption due to its entrenched aerospace manufacturing ecosystem anchored by key OEMs. Meanwhile, the Asia-Pacific region exhibits the fastest growth rate, fueled by expanding domestic airline fleets in emerging economies and indigenous manufacturing initiatives led by entities such as AVIC Shenyang Aircraft Company Ltd.
In-Depth Regional Review
North American growth is underpinned by continuous defense outlays and major assembly plants operated by Lockheed Martin Corporation. In Europe, stringent environmental regulations enforced by the European Union drive rapid adoption of lightweight Carbon Fiber Reinforced Polymers (CFRP), with key contributions from advanced research clusters in France, Germany, and the UK.
Strategic Positioning of Leading Companies
Industry leaders leverage specialized product portfolios to capture high-margin segments. For instance, Allegheny Technologies Incorporated and Arconic Corporation focus on advanced metallurgy for engine components, while Novelis Inc. optimizes aluminum rolling technologies for structural airframe skins and wing spars.
Porter's Five Forces Analysis
The threat of new entrants remains low due to prohibitive capital expenditure requirements and stringent FAA qualification hurdles. Bargaining power of suppliers is moderate-to-high for specialized raw materials like aerospace-grade cobalt and titanium sponge, while buyer power is concentrated among major duopolistic airframe manufacturers.
SWOT Analysis of the Global Sector
Strengths include high entry barriers and advanced technological moats in composite manufacturing. Weaknesses involve high sensitivity to raw material volatility. Opportunities center on urban air mobility platforms, whereas threats include macroeconomic trade friction and geopolitical supply disruptions affecting critical mineral imports.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw mineral extraction and refining, progressing to alloy smelting and intermediate form production by firms like Constellium SE. Mid-stream tier-1 suppliers fabricate complex assemblies before final integration by airframers such as The Boeing Company and Dassault Aviation.
Investment Insights and High-Potential Areas
High-potential investment avenues target sustainable aviation fuel-compatible structural components and recycling technologies for carbon fiber composites. Capital allocation toward Nickel-Based Super Alloys manufacturing offers superior margin security given the long-term commitments in military and commercial turbine engine upgrades.
Conclusion and Strategic Takeaways
The Aerospace Materials Market represents a highly lucrative arena driven by technological substitution and fleet modernization. Stakeholders must prioritize sustainable manufacturing practices and secure resilient supply chains to capitalize on the path toward the 86.31 Billion milestone by 2033.
Research Methodology for Baseline Estimates
Our analytical framework triangulates data from primary stakeholder interviews with chief procurement officers, secondary trade registries, and macroeconomic indicators. Baseline estimates for 2026 at 45.29 Billion were validated through cross-referencing company financial reports and customs data across major manufacturing jurisdictions.
Scope of the Report and Coverage Parameters
This report covers global demand dynamics across commercial aviation, business jets, civil helicopters, and military aircraft sectors from 2027 through 2033. Limitations exclude unregulated light sport aircraft and uncertified experimental builds, maintaining strict focus on airworthiness-certified material grades.
Recent Developments in Strategic Partnerships and Product Launches
Recent industry momentum features strategic supply agreements between composite specialists like Hexcel Corporation and major engine builders such as MTU Aero Engines. Innovations focus on recyclable thermoplastic matrices and advanced alloy coatings designed to withstand heightened turbine temperatures and extend maintenance intervals.